
Circle Introduces Bitcoin-Backed USDC Loans for Institutional Users
0
0
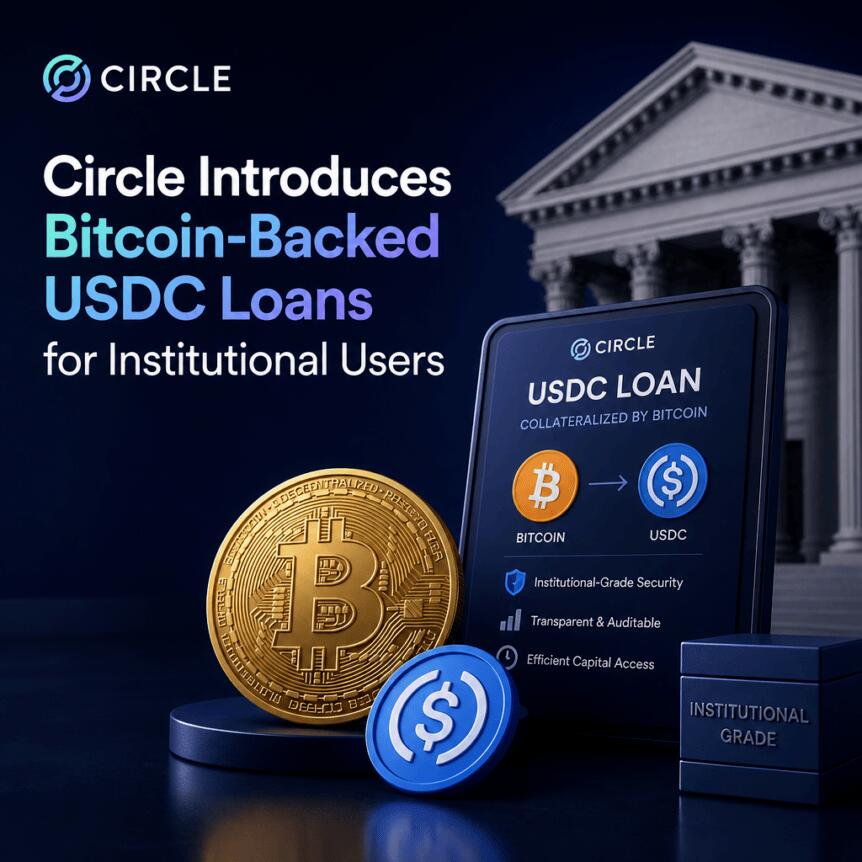
Stablecoin issuer Circle is moving deeper into regulated crypto lending with a new Bitcoin-backed borrowing service designed for institutions. Through its Circle Mint platform, eligible customers can deposit Bitcoin, use Circle’s wrapped token cirBTC as collateral, and borrow USDC via supported onchain lending markets.
Circle says the rollout aligns with a broader infrastructure push around its Arc network, which is positioned as a layer-1 for stablecoin-based payments and financial services. The borrowing service—called Digital Asset-Backed Borrowing—adds a new way for Bitcoin holders to access USDC liquidity without handing custody of the underlying assets to the lending venues themselves.
Key takeaways
- Circle’s new service lets eligible Circle Mint customers use Bitcoin as collateral to borrow USDC on supported DeFi lending protocols.
- The borrowing workflow uses cirBTC as the collateral token, which Circle says is backed 1:1 by Bitcoin held in custody by Circle National Trust.
- Borrowing terms such as rates, collateral requirements, and liquidation thresholds are determined by the third-party lending market, not by Circle.
- Circle plans to start with Morpho and later add Aave and other protocols.
- New York clients are excluded from the offering.
How Circle’s Bitcoin-backed borrowing works
Circle’s announcement details a custody-aware structure aimed at institutional users. Under Digital Asset-Backed Borrowing, eligible Circle Mint customers can deposit Bitcoin and mint cirBTC, Circle’s wrapped Bitcoin token. That cirBTC is then supplied as collateral to supported third-party lending markets.
Circle states that borrowed USDC is credited directly into the customer’s Circle Mint balance. From there, the customer can use USDC as needed—while the collateral posting and liquidation mechanics are governed by the specific lending protocol used.
Importantly, Circle positions this as a model that keeps the customer’s collateral control in the foreground. The company says the collateral is supplied via a customer-controlled wallet to the third-party DeFi protocol rather than lent out directly by Circle. Circle also characterizes the arrangement as overcollateralized, meaning borrowers must post more value in collateral than the amount of USDC borrowed.
Circle also notes that parameters affecting the position—such as borrowing rates, required collateral, and liquidation thresholds—are set by the third-party lending market. That design shifts the day-to-day risk and mechanics to the underlying DeFi venue, while Circle focuses on eligibility, the wrapping process, and the institutional onramp.
Morpho first, with Aave and others planned
For the initial launch, Circle is supporting Morpho as the first lending protocol for cirBTC-collateralized borrowing. Circle indicated that it plans to expand support to Aave and additional lending markets over time.
Separately, Circle’s timing matters for users watching Arc’s ecosystem. The service rollout coincides with cirBTC going live on Arc. According to Circle, cirBTC was launched on Ethereum in June, and its network availability is now expanding.
Circle also confirmed that it intends to connect these institutional borrowing flows to the broader Arc environment—an approach that could reduce friction for participants that prefer to use USDC as a settlement and payments asset within a single chain ecosystem.
Why the structure matters for institutions
Circle’s model reflects a recurring institutional demand in crypto: access to borrowing and leverage-like liquidity strategies without disrupting existing custody arrangements. By using cirBTC—backed 1:1 by Bitcoin held in custody by Circle National Trust—Circle provides a path to onchain credit while keeping a clear chain of custody and token backing on the issuer side.
This stands in contrast to some earlier institutional designs aimed at preserving underlying Bitcoin custody without wrapping. In a previous approach described earlier in the market, Lombard partnered with Bitwise to develop a system for borrowing against BTC held in custody, with Morpho supplying lending infrastructure. That model, as described in coverage at the time, was designed to avoid converting the underlying Bitcoin into a separate wrapped asset—opting instead to keep the Bitcoin in custody without using wrapping or bridging.
Circle’s decision to introduce cirBTC instead indicates a different tradeoff: the wrapped token enables easier integration with existing lending markets that support ERC-asset collateral, while Circle can still point to a specific backing mechanism for cirBTC.
More broadly, the development fits a pattern of institutional-oriented lending platforms emphasizing “qualified custody” and controlled collateral rather than open-ended asset movement. Earlier, Anchorage Digital partnered with Kamino to enable institutions to borrow against staked Solana held at Anchorage Digital Bank, avoiding a direct requirement to move collateral out of qualified custody. And BitGo expanded its institutional lending efforts with a portfolio-based framework, enabling multiple assets to serve as collateral depending on the structure of the financing.
In that context, Circle’s offering is best understood as an additional layer to the institutional lending stack—one that combines an issuer-backed collateral token, an institutional balance interface through Circle Mint, and DeFi lending mechanics executed on third-party protocols.
Arc mainnet timing and the USDC-centered roadmap
The borrowing service arrives just days after Circle rolled out the Arc mainnet, a layer-1 network designed around stablecoin payments and financial market use cases. Circle’s Arc positioning includes USDC as the native gas token, and support for tokenized assets such as BlackRock’s BUIDL and Circle’s USYC, according to earlier coverage.
That sequencing matters because it suggests Circle is aligning two different parts of its business: the transport layer (Arc) and the financial layer (stablecoin issuance, tokenization, and now institutional borrowing). For investors and builders, it also raises practical questions about where collateral and liquidity will concentrate—whether users will continue to rely primarily on Ethereum for DeFi borrowing, or whether Arc’s stablecoin-native design will draw activity from the start.
At the same time, the biggest determinants of user experience and risk remain anchored in the third-party lending markets that set borrowing rates and liquidation parameters. That means the real impact for end users may vary quickly depending on how Morpho (and later Aave and others) structure collateral factors and liquidation thresholds for cirBTC.
What to watch next
Circle’s next milestones—adding Aave and expanding the lending venue lineup, as well as observing how cirBTC usage develops across Arc versus Ethereum—will reveal whether this is merely an incremental product launch or a step toward a more standardized, issuer-coordinated institutional borrowing workflow. For now, institutional participants should pay close attention to protocol-specific borrowing terms, liquidation behavior, and eligibility constraints, including the exclusion of New York clients.
This article was originally published as Circle Introduces Bitcoin-Backed USDC Loans for Institutional Users on Crypto Breaking News – your trusted source for crypto news, Bitcoin news, and blockchain updates.
0
0


 Manage all your crypto, NFT and DeFi from one place
Securely connect the portfolio you’re using to start.


