
Solana loses 6.4 percent of its stablecoin reserves: what counts for your sell order now
0
0
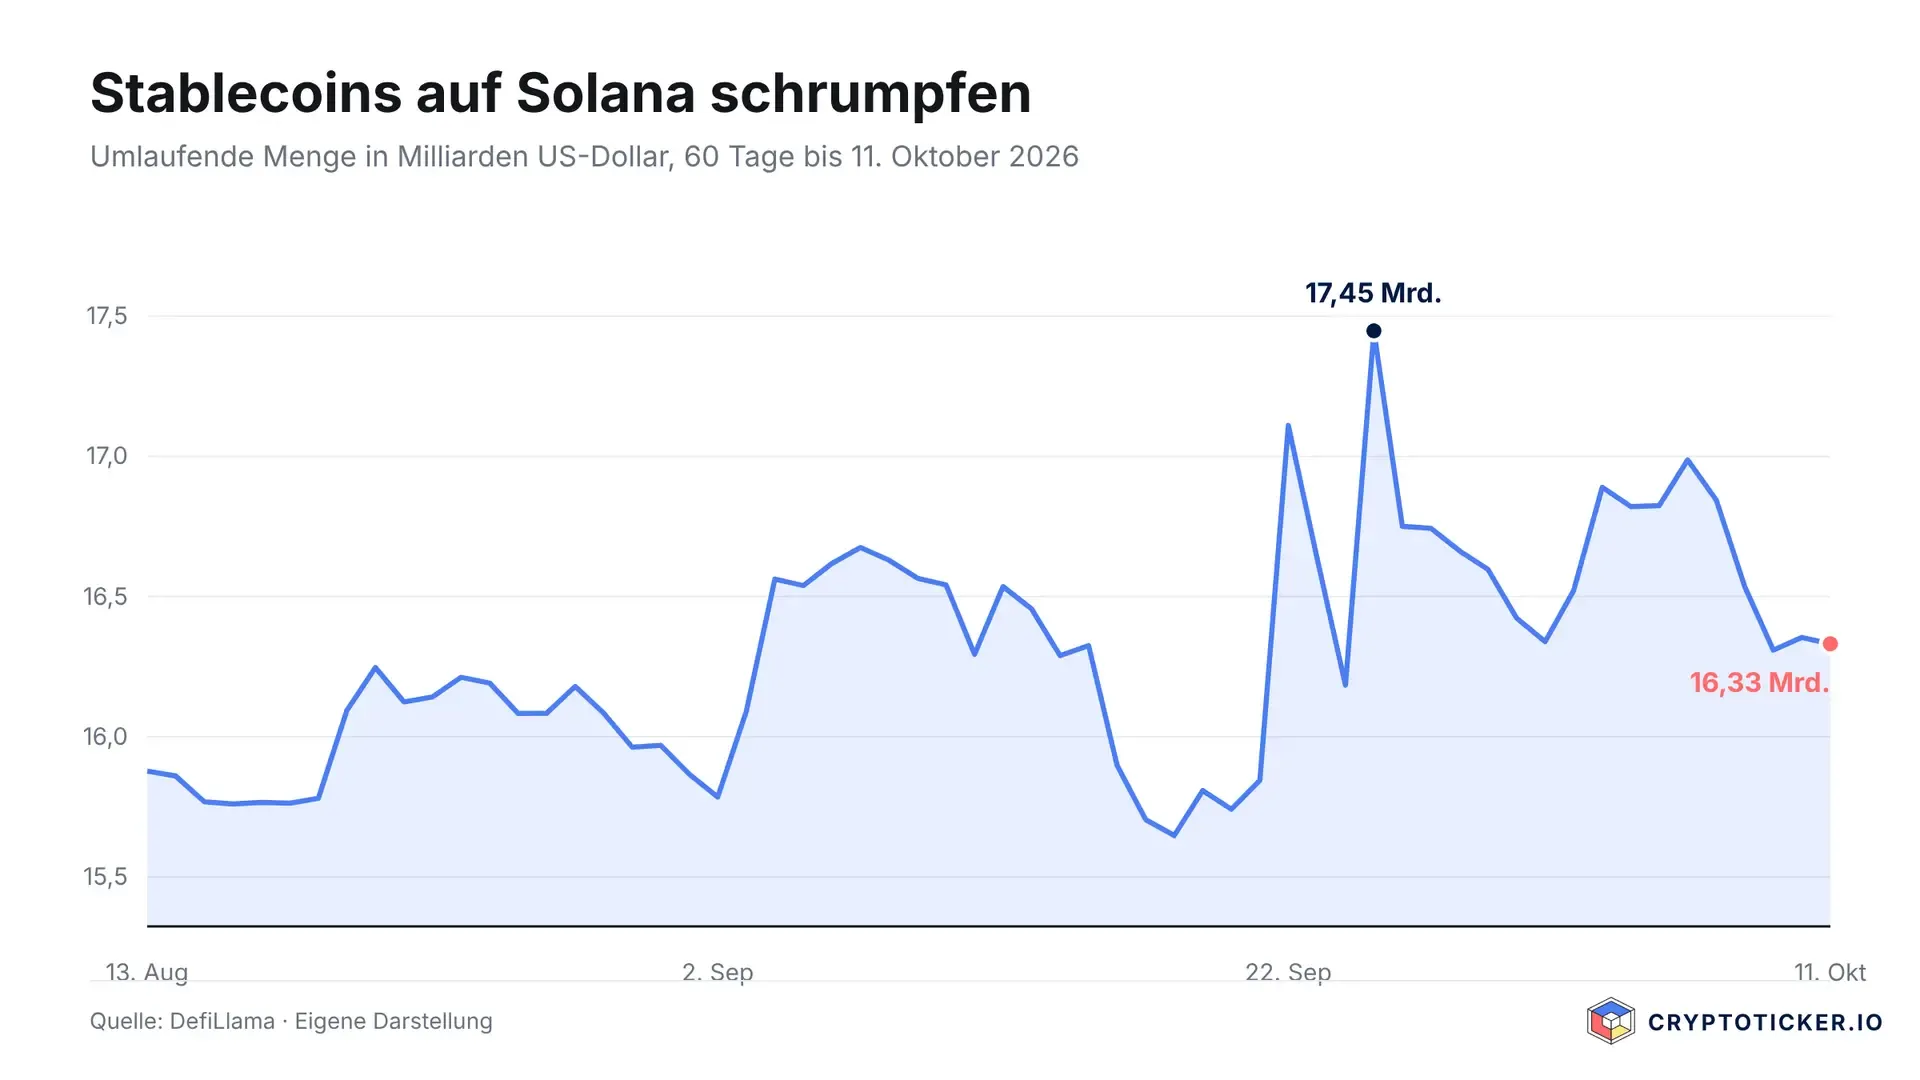
Solana holds $16.33 billion in stablecoins on Sunday afternoon. On September 25 the figure was $17.45 billion. Around $1.12 billion has therefore left the chain in 16 days, just under $70 million a day on average. That is 6.4 percent of the entire stablecoin cushion, and it is the number that reaches you when you sell, earlier than any price headline does.
Stablecoins are a blockchain's cash. Sell something on Solana and you will almost never be credited in euros; what arrives is a dollar token. When that stock shrinks, the other side of your sell order shrinks with it. The price itself says nothing about this: SOL traded at $111.79 at around 16:43 UTC on October 11, up 1.48 percent in a day, with a daily high of $111.84 and a daily low of $108.94. Over a week it is down 7.8 percent, over 30 days up 9.5 percent. The figures come from CoinGecko.
Stablecoins on Solana: $1.12 billion less than on September 25
The DefiLlama time series puts the peak on September 25 at $17.45 billion. The stock has fallen in steps since then, interrupted by two brief counter-moves in early and mid-October. The reading on October 11 is $16.33 billion. Add up all the individual dollar tokens and the result is $16.29 billion; the small discrepancy between two queries of the same database comes from different sampling times and is not smoothed over here.
What counts is the direction of travel, and the second decimal place is beside the point. A drop of 6.4 percent in a little over two weeks is more than noise. For comparison: over the preceding 60 days the stock oscillated between $15.6 billion and $17.5 billion, so the distance from trough to peak came to around $1.9 billion over two months. A third of that span has now been worked off in 16 days.
What a chain's stablecoin cushion actually tells you
The stablecoin cushion is the sum of all dollar-pegged tokens issued on a blockchain. It is no use as a price indicator, because it is a stock figure: what gets measured is how much sale-ready capital is parked on the chain. Unlike the SOL price, it does not hang on the market price. A dollar token stays worth a dollar even when SOL falls. If the total drops anyway, somebody has redeemed tokens or bridged them to another chain.
That is exactly what makes the metric useful. When the price falls, the dollar value of every locked coin falls automatically with it, without a single investor having done anything. Stablecoins carry no such arithmetic artefact. Every billion that disappears is a decision by somebody who wanted their money somewhere else.
Slippage when selling: how a thinner cushion hits your order
Slippage is the difference between the price you see when you submit an order and the price at which it is actually filled. It occurs when your order is larger than the other side available at the best price and therefore eats through several price levels.
The mechanism takes two sentences. On a decentralised exchange on Solana, every liquidity pool holds a coin on one side and a dollar token on the other. The fewer dollar tokens sitting in those pools, the more a sell order moves the price against you, because it accounts for a larger share of the pool.
For small amounts this stays invisible. Sell 500 euros of SOL and $1.12 billion less cushion will not register. It becomes visible at four- and five-figure amounts, earlier than that for illiquid Solana tokens away from the big names, and always when many holders want to sell at once. SOL's 24-hour trading volume stands at $1.70 billion according to CoinGecko, with a market capitalisation of $65.85 billion.
Solana against Ethereum and Tron: where the stablecoins sit
Among the chains, Solana remains a mid-sized venue. On the same data, Ethereum holds around $145 billion in stablecoins and Tron around $95 billion, against a good $16 billion on Solana. Solana therefore carries about a ninth of the Ethereum cushion.
That order of magnitude matters more for your own trading than it sounds. The gap explains why large sales move the price more on Solana than on Ethereum, and why an outflow of $1.12 billion weighs far more in percentage terms here. On Ethereum the same amount would have been a decline of 0.8 percent.
USDC, USDT and USD1: which stablecoins on Solana are authorised in the EU
Trading from Germany calls for knowing not only how many dollar tokens sit on Solana, but which ones. The breakdown on October 11 looks like this: USDC from Circle leads with $6.79 billion or 41.7 percent, followed by USDT from Tether with $2.87 billion or 17.6 percent. Then come USD1 from World Liberty Financial with $1.41 billion, USDGO with $1.29 billion, BlackRock's tokenised money market fund BUIDL with $0.93 billion, PayPal's PYUSD with $0.71 billion, USDG with $0.63 billion and Ethena's crypto-backed USDe with $0.48 billion.
Under the European Markets in Crypto-Assets Regulation, MiCA for short, a dollar token needs an authorised issuer in the EU before it may be offered on licensed trading venues. The technical term is the e-money token: a crypto asset that replicates exactly one official currency and is issued by a supervised e-money institution.
The register of the European Securities and Markets Authority, ESMA, lists as of September 30, 2026 USDC and EURC from Circle Internet Financial Europe, supervised by the French ACPR, as well as USDG from Paxos Issuance Europe under the supervision of Finland's FIN-FSA, among others. USDT, PYUSD and USD1 have no entry.
Apply that to the stock and a finding emerges that appears in none of the usual market overviews: of the $16.29 billion on Solana, $7.42 billion or 45.5 percent sits in tokens with EU authorisation, and $5.00 billion or 30.7 percent in tokens with no ESMA entry. The remainder is spread across structures that are not e-money tokens at all, such as the BUIDL fund share and the crypto-backed USDe.
Holding USDT is not thereby prohibited. Owners may keep it and transfer it to their own wallet. What is missing is trading on venues with a MiCA licence. The licensing duty falls on the trading venue, while the holder is unaffected.
Revolut on August 31: a forced conversion over holders' heads
How practical this gets was on show on August 31, 2026. Revolut converted European customers' USDT holdings without those customers having to act themselves. That assessment comes from our own stablecoin comparison with MiCA status, as of October 2, 2026.
The episode is the pattern that counts: the timing belongs to the provider, and the investor has no say in it. Anyone holding an unauthorised dollar token on a European trading venue bears the risk that the position is turned at a price and on a date set by somebody else. On your own Solana wallet that risk disappears, leaving the question of where the token can later be swapped back into euros.
Check before you sell: what depth your venue really offers
The chain's stablecoin cushion is a background figure. What hits your order is the depth at the venue where you actually trade. Three things can be looked up in a few minutes.
First, the order book of a centralised exchange: it shows how much of the other side sits within 1 and 2 percent of the current price. If your planned sale is larger than the sum inside that band, you will move the price yourself. Second, the expected slippage display that every larger decentralised exchange shows before confirmation; it calculates the effect for your exact order size. Third, the question of which dollar token you end up holding, and whether your venue swaps that token back into euros.
Split the order if you are moving larger amounts. Two or three partial sales spread over a few hours cost a little more in fees and save more than they cost when the cushion is thin.
DeFi TVL on Solana: $6.19 billion and 53 percent below the 2025 high
Alongside the stablecoins, DefiLlama measures the total value locked in Solana applications. It stands at $6.19 billion on October 11. On October 5 it was $6.63 billion, a decline of 6.6 percent in six days, so at the same pace as the stablecoins.
Over 30 days, by contrast, it is up 7.6 percent, because capital flowed in during September. The value is 53.2 percent away from its peak of $13.24 billion on September 14, 2025. That figure does contain the price effect, though: when SOL falls, the dollar-denominated TVL falls with it. The stablecoin series is the cleaner signal for precisely that reason.
Set against our own earlier coverage: on the evening of October 10, SOL stood at $110.28 when the US spot ETFs lost $24.8 million net for the first time after 14 weeks of inflows. The price has gained 1.37 percent since then, while the stablecoin cushion has carried on shrinking. The detail on the ETF week is in our report on the end of the inflow streak at Solana ETFs. On the technical side, block times have been running at 200 milliseconds since October 9, as set out in our assessment of the halved slots; the chain has grown faster, in other words, while the capital drains away.
The editorial team's view: the outflow is a warning sign, not an alarm
In the editorial team's judgement the finding carries medium weight. Three pieces of evidence support it: the decline has run in the same direction for 16 days, it shows up in the TVL as a second, independently collected measure, and it coincides with the first ETF outflow after 14 weeks. Against it stands the fact that $16.33 billion is still above the level of mid-August, when the cushion stood at $15.88 billion, and that over 30 days the chain records 7.6 percent more locked capital in the same period.
What this amounts to is a cooling after a strong September, well short of a flight. If you hold SOL and have no intention of selling, nothing follows from it. If you plan to move larger amounts in the coming weeks, reckon with somewhat more slippage than in September and plan partial sales. None of this is a buy or sell recommendation, and total losses are possible with crypto assets.
Solana reserves: $1.12 billion less buffer than on September 25
- Check which dollar token you end up holding after a sale and match it against the supervisor's register. The entry in the ESMA register is what governs, and the name of the token is no guide.
- Check the depth of your trading venue within 1 and 2 percent of the price before placing a larger order. Which exchanges operate in Germany with a licence is set out in the crypto exchange comparison.
- Holdings you want to keep for longer have no business on a trading venue. The differences between the devices are set out in the hardware wallet comparison.
This article draws on the public series from DefiLlama on the stablecoin supply on Solana and on the European Securities and Markets Authority's register for the Markets in Crypto-Assets Regulation.
(As of October 11, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)
0
0

 Manage all your crypto, NFT and DeFi from one place
Securely connect the portfolio you’re using to start.


